

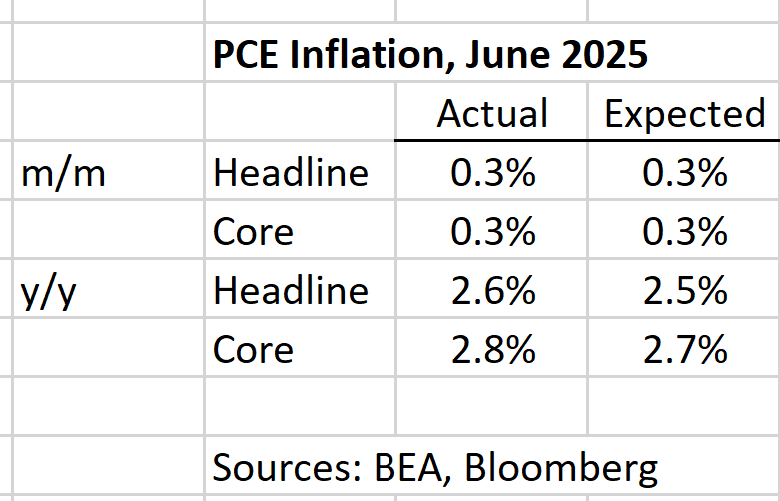
Core PCE inflation, the key inflation gauge tracked by the Federal Reserve, rose 0.3% in June and 2.8% over the past year, the latter rate being a tick higher than expected (see table). Headline inflation (including food, energy) also came in a touch hotter than expected on a yearly basis, up 2.6%. Both yearly rates are a pretty long way from the Fed’s 2% target, and given that the tariffs are now clearly taking hold, I’m concerned about their direction of travel.
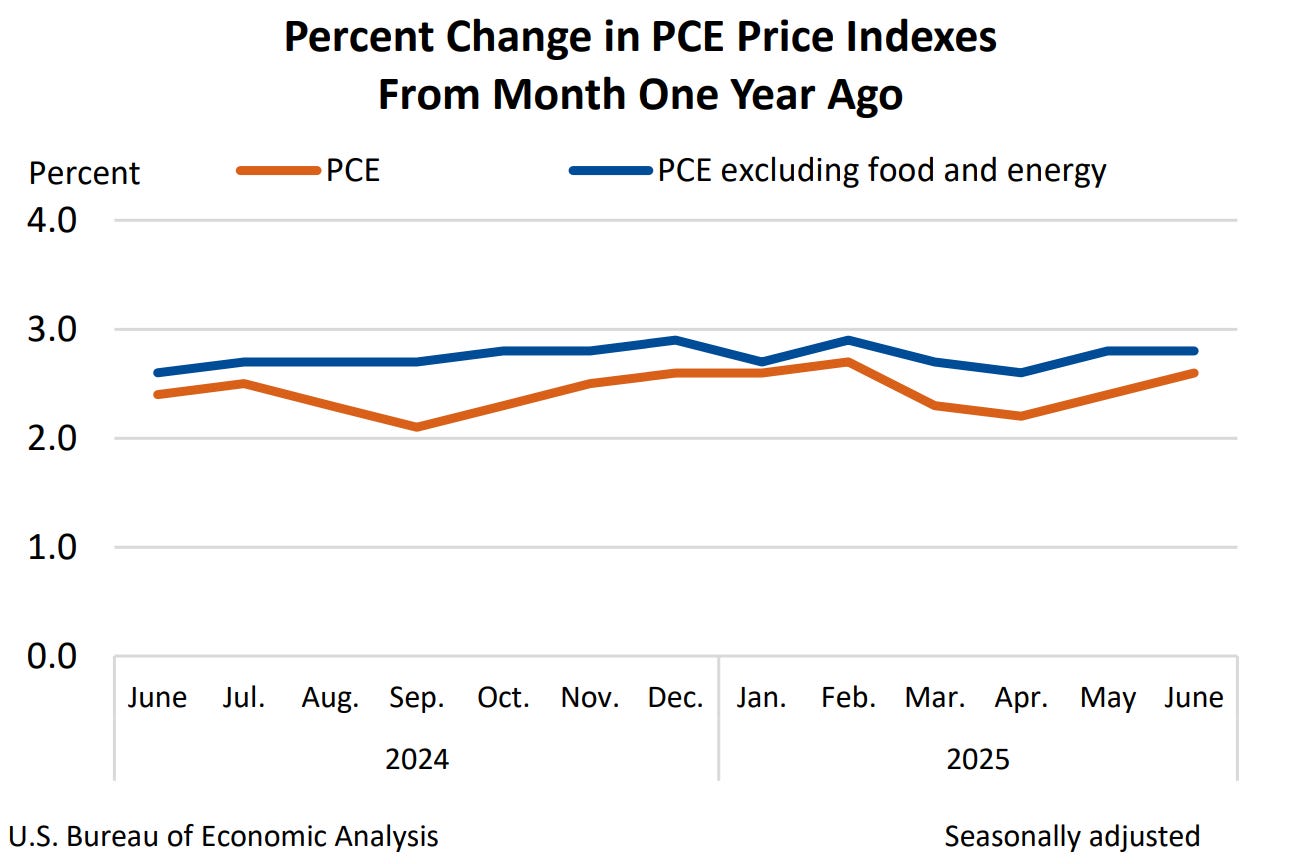
The figure below shows the recent trends in yearly PCE inflation, and they don’t look great. Core is stuck well-above target, and the overall index is ticking back up. To be clear, these are far from alarming rates of inflation, but their recent movements are concerning, especially given that we are now seeing two quite challenging developments in this space.
One, Trump’s trade war is escalating, with tariffs spewing out of the White House like toxic smoke from a dumpster fire, and two, we’re now seeing consumer price-passthrough at both anecdotal and statistical levels.
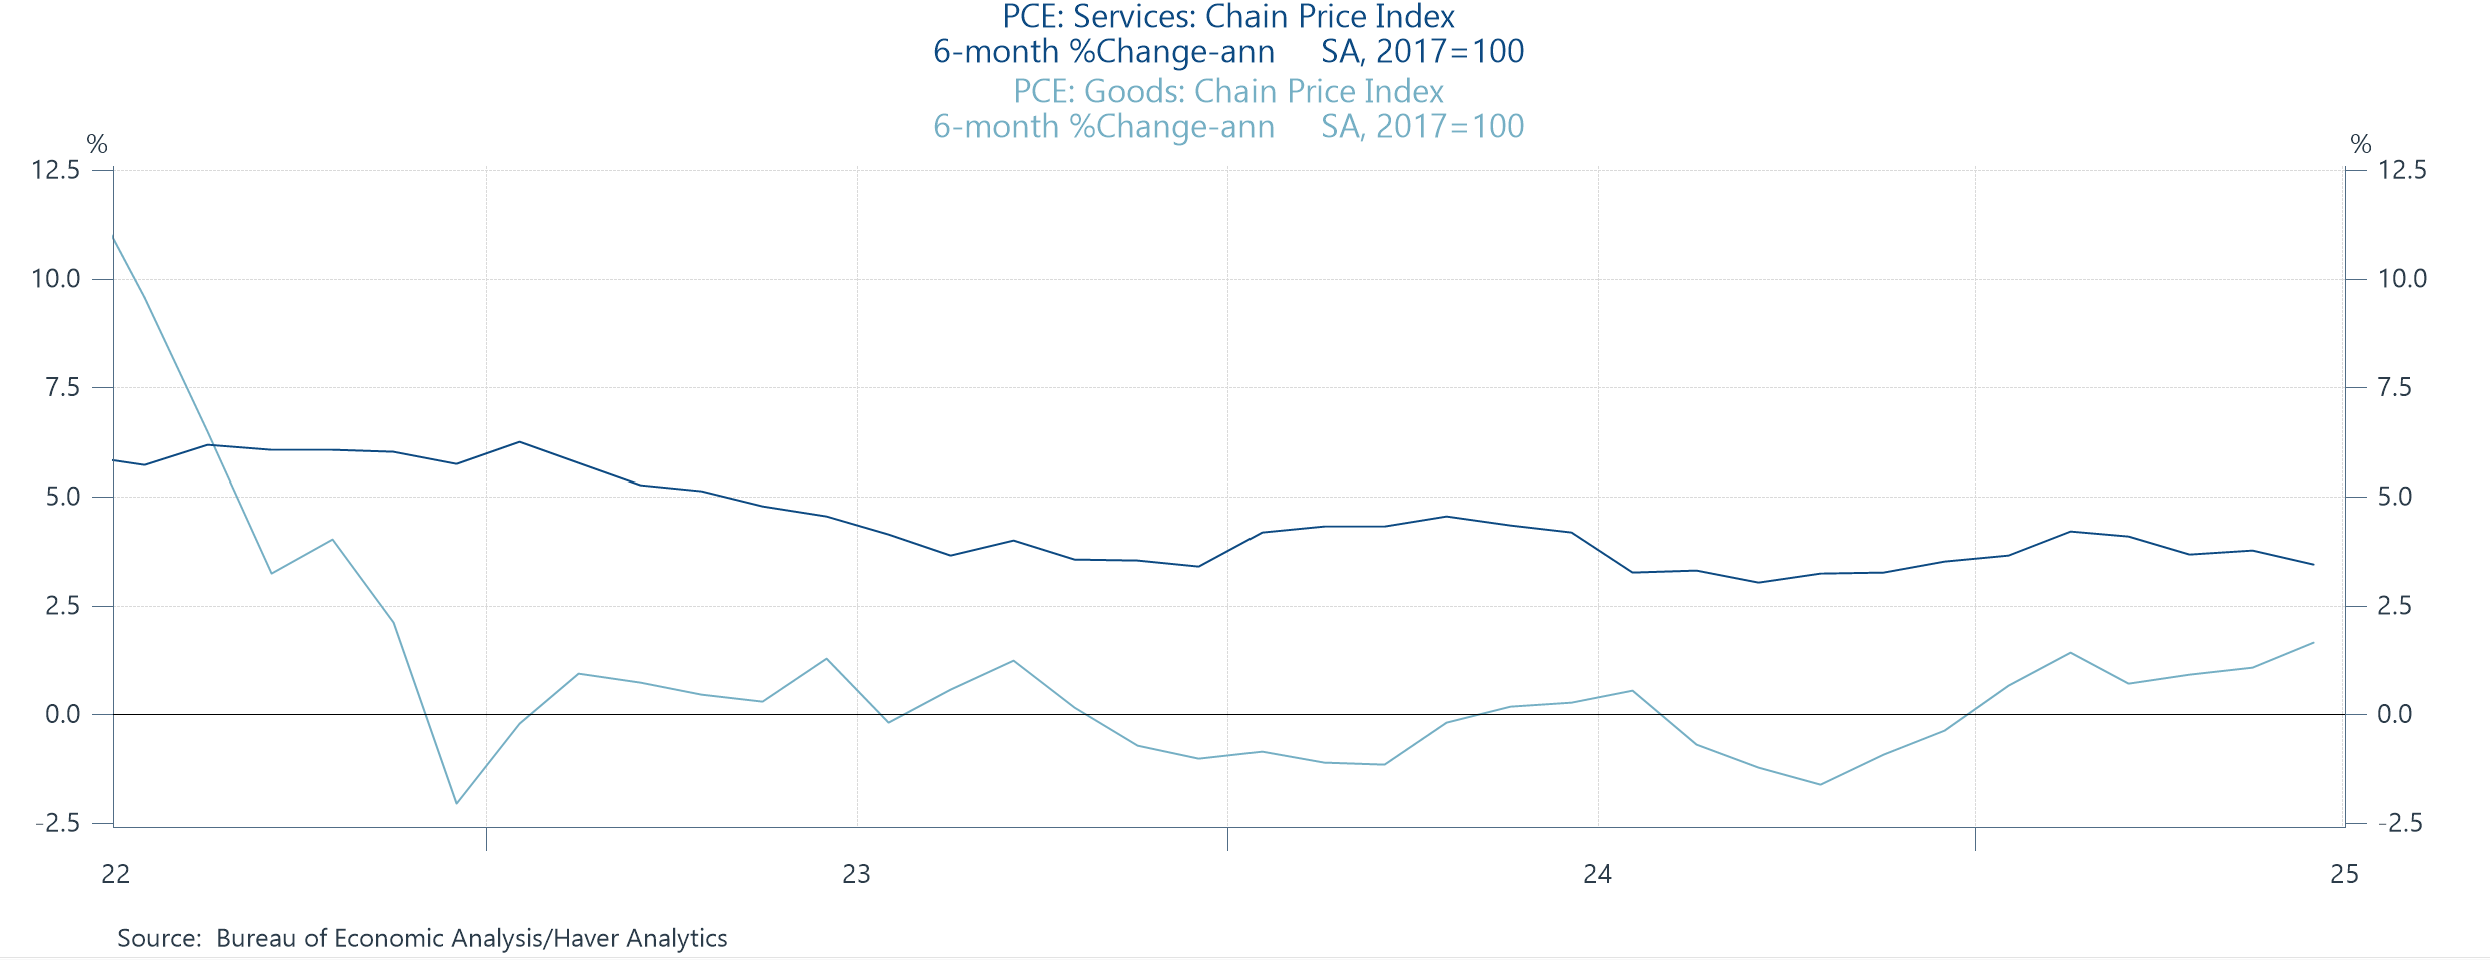
This next figure gets under the hood a bit re statistical evidence on recent PCE inflationary pressures. It shows 6-month annualized growth rates (a helpful metric to zoom in on recent momentum) of the two broad components of the index: goods and services. Services inflation has been pretty flat, and even trending down very slightly in recent months. But goods inflation, which is where we’d expect to see tariff-price pressures, has crept up.
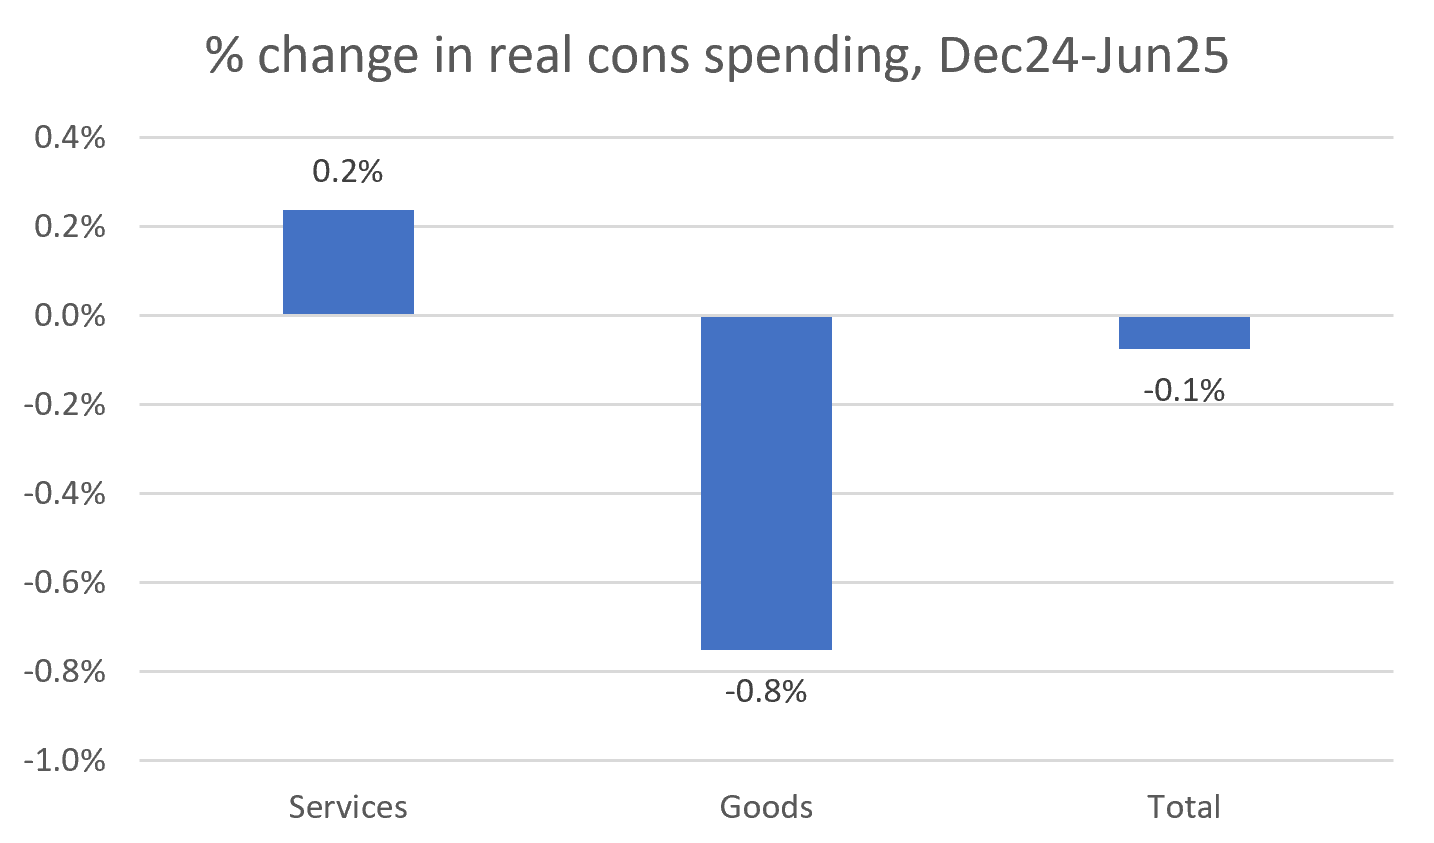
Readers know I’ve been closely tracking spending, making a biggish deal out of the fact that real consumer spending—a key source of economic growth throughout this expansion, has been flat this year. Real spending was up slightly—0.1%—in June, but it’s still flat for the year. Real spending was down 0.2% through May, and it’s now down 0.1% through June, with spending on goods accounting for the overall flatness. For historical context, this same change over the previous year, i.e., Dec23-Jun24, was 0.9%. IOW, we’re seeing a clear deceleration.
So, what’s the bottom line here?
For one, there’s a whiff of stagflation in these data. Prices are sticky, if not trending up a bit, especially for goods, relating to the fact that goods imports are increasingly tariffed. Real consumer spending, though it ticked up for the month, is flat for the year, which is a big reason why we learned yesterday that growth for the first half of the year, at 1.2%, has been subpar.
But the real concern is where this is headed. Clearly, tariffs, not to mention deportations that are particularly punishing to certain sectors, like meatpacking, construction, and health services, are taking a toll on prices and production. But unlike the markets, these impacts are a lot more gradual. Trump has shown that a market dive will shift him into TACO mode, but the slower burn we’re seeing here is unlikely to do so.
One is reminded of the Hemingway line from The Sun Also Rises wherein a character explains how he went bankrupt: “Two ways. Gradually, then suddenly.”
Can we still trust the numbers?
Thanks for update. The one thing I have noticed for a while now is the decrease in the size, weight or portion of a good. The package is the same but the content in the package of food is less. The price may be the same but number or size of Cookie make be fewer or smaller. If you want that cookie you will need to buy it more often. How is this phenomenon taken into consideration as economist chew thru the data?